What is a Carbon Border Adjustment Mechanism?
Carbon pricing is an instrument that captures the external costs of greenhouse gas (GHG) emissions. UK manufacturing has had a carbon price since 2005 when the EU Emissions Trading Scheme was introduced. There is acknowledgement of the risk of ‘carbon leakage’, currently addressed through Free Allowances to exposed sectors.
Carbon leakage occurs because some competitor regions overseas (e.g. US Gulf Coast, the Middle East, West Africa and India) pay little or no carbon costs. This tilts the market against Britain, making imports cheaper even when they are more polluting. The result: we export jobs, emissions and investment, and undermine our own resilience. We also undermine our ability to credibly achieve net-zero.
In 2023, the Government consulted on “potential policies including a carbon border adjustment mechanism (CBAM); product standards, and other policy measures to help grow the market for low emission products, as well as support the implementation of carbon leakage policy more broadly.” The details can be found here: https://www.gov.uk/government/consultations/addressing-carbon-leakage-risk-to-support-decarbonisation
The intent of a CBAM is to treat domestic and imported goods in an equal way by applying a charge on carbon emitted during the production of imports. By levelling the playing field with domestic producers, the aim is to mitigate the risk of carbon leakage.
CBAM consultation announcement in Autumn Budget 2026
In the Autumn Budget, a consultation was announced to seek views on the feasibility and impacts of CBAM sectoral scope expansion to refinery products: Carbon Border Adjustment Mechanism (CBAM): a consultation on sectoral scope expansion to include refinery products. The link to the consultation can be found here.
Fuels Industry UK response to Autumn Budget 2026
Elizabeth de Jong, Chief Executive of Fuels Industry UK, said:
“Our refineries are the foundation of both the UK’s energy security and our wider economic success. We are therefore pleased that Government has today recognised this in their Budget, by announcing they will bring refined products into scope of the Carbon Adjustment Mechanism (CBAM), helping to level the playing field for UK refineries.
“Whilst today’s recognition from Government of the importance of the UK’s fuels industry to both our energy security and our economic success is welcomed, the lack of a firm target date to implement a CBAM for refined products will be a concern for the UK’s remaining refineries. Policy certainty is needed for future investment decisions.
“With carbon costs, which are not paid by importers, set to triple by 2030 and UK refineries already unable to compete on a level playing field with global competitors, the sector urgently needs the UK Government to set a firm timeline towards the introduction of a CBAM for the sector in 2029 which we believe is entirely feasible.
“We will now work closely with Government to ensure that a well-designed, effective CBAM - including the necessary export mechanism - is delivered as quickly as possible and we will be making that case in our response to the consultation opened today”.
Why does the UK refining sector need a CBAM?
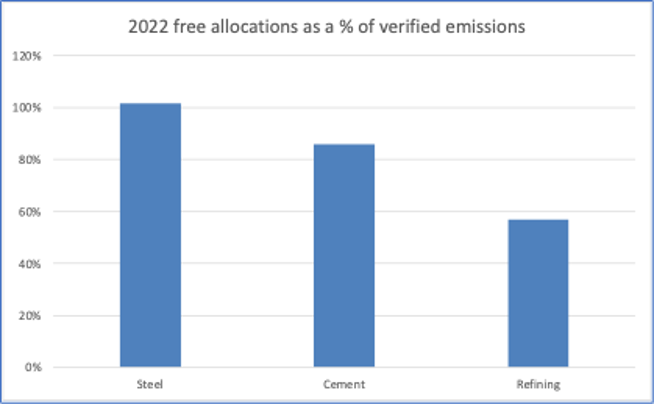
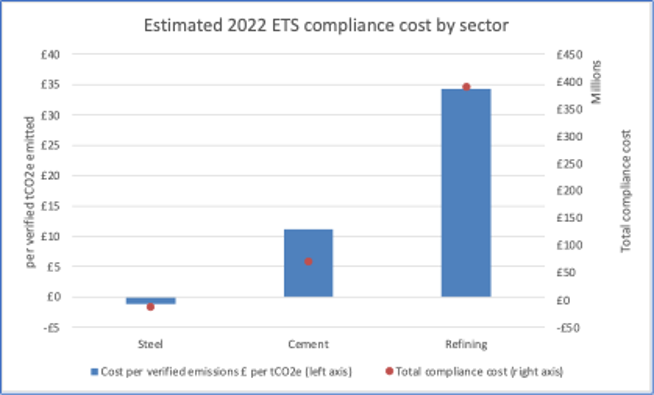
As described above, UK refiners operate in a global market where many international competitors face no equivalent carbon costs. This creates a structural disadvantage for UK production and increases the risk of de‑industrialisation by undermining the case of making long‑term investments in the domestic refining sector. Factors such as trade patterns and emissions intensity mean that refineries are at a very high risk of carbon leakage, and the UK government recognizes this. However, and as the tables below show, the refining sector faces higher emissions compliance costs than other sectors. This is due to a more challenging product benchmark.
Is there a methodology for a refining CBAM?
Fuels Industry UK, working with consultants Wood Mackenzie, submitted a feasible methodology for applying a CBAM to refined fuels in mid-2025. Later that year, in the Autumn Budget, the Government committed to explore the inclusion of refined products within the UK CBAM. The recent decision not to include refineries in the CBAM from 2028 was announced by the Exchequer Secretary in a letter received in March 2026, despite the sector meeting the three tests for CBAM inclusion set by Treasury.
With energy security and the UK’s growing reliance on imported fuels under heightened public scrutiny, the sector was pleased to see in the 2026 Autumn Budget, a consultation was announced to seek views on the feasibility and impacts of CBAM sectoral scope expansion to refinery products: Carbon Border Adjustment Mechanism (CBAM): a consultation on sectoral scope expansion to include refinery products.
Key features of the proposed methodology
- Simple and pragmatic approach - This method provides a clear, practical way to apply a CBAM to the refining sector without adding unnecessary complexity.
- Single carbon intensity for similar fuels - Fuels with similar carbon intensities are assigned a single value, supporting simplicity and consistency.
- Uses only existing data - The approach relies on data that is already available. The data requirement is emissions figures that are already collected by the ETS authority and fuel volume figures collected by HMRC for tax purposes.
- Framework for assessing overseas refineries - Where overseas refinery data, systems or assurance processes are not available, default factors can be applied, ensuring the mechanism remains workable and fair.
View the methodology here.
How would HMT calculate a CBAM?
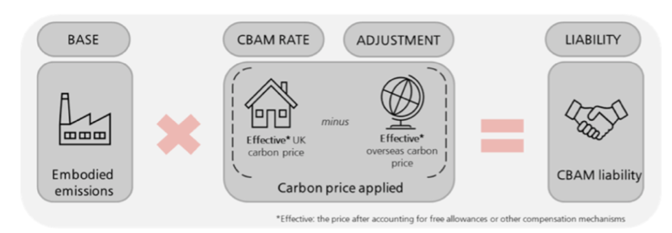
An explicit carbon price puts a £/tCO2e liability directly on greenhouse gas emissions produced through the manufacture of goods that are imported into the UK.
The effective carbon price in the UK is the actual net price paid by UK manufacturers after accounting for the impact of free allowances and other support mechanisms.
CBAM liability therefore based on carbon price differential between the UK and the country where products were produced; and embedded carbon intensity of the imports.
What would a CBAM achieve ?
A well‑designed CBAM for fuels ensures that UK decarbonisation does not come at the cost of UK industrial decline. It supports a level competitive playing field, long‑term investment in domestic refining and UK energy security. Introducing an appropriate mechanism would help to mitigate some of the ETS compliance cost on the manufacture of exports and further reduce the risk of carbon leakage.
If Government introduces a CBAM: Carbon leakage will be prevented, and UK refineries have a better chance of attracting the investment necessary to decarbonise.
If Government fails to act: Refineries in the UK will continue to suffer from a lack of inward investment and the UK economy will move towards a fuel importing economy, with implications for energy security. Furthermore, refineries overseas continue to emit CO2that UK refineries once did. In fact, evidence suggests they have a greater environmental impact than was the case when refineries were in the UK.